
Apparently, this came in in April 2026. We missed that. It was announced in the budget that this would be made permanent. This applies to the first 10,000 miles. After that distance the rate is 35p/mile.
In mid September the FCA lead for financial crime, Stephen Smart, spoke at the Law Society's economic crime conference. It seems to be the start of their engagement with the solicitors profession about their anticipated approach to AML regulation when they take that over from the SRA. He acknowledged that there needs to be more engagement and that they needed to win the trust of the legal profession. There would me more engagement over the coming months. Good. It need to happen.
Some clarity about the timetable. The Financial Services and Markets Bill is currently going through parliament and should receive royal assent early 2028. That will start the process with the FCA assuming responsibility for regulating AML compliance from the end of 2028. That will start the transition period which will end in 2030.
How many solicitors firms are affected? As of April 2025, 5,569 firms fell within the scope of the money laundering regulations. More than 1,000 of these firms had just one practising solicitor.
It should be remembered that it is not just affecting solicitors. It is also affecting the accountancy profession and many others - a total of 22 professional bodies. The goal is to create a single, unified professional services supervisor to improve consistency and enforcement.
Stephen Smart said: "‘We will not take a one-size-fits-all approach [and] we will not be overloading firms with requests and paperwork. We will be creating friction for criminals but letting everyone get on with their business… We can do it with a proportionate, predictable and technology-enabled approach." He talked about working in partnership and not wanting a 'them and us' approach.
(A lot of this information is courtesy of this LS Gazette)
We provide a lot of AML support to businesses in the Legal Sector. Please see below for a summary and links for further information. (Watch this space for assistance coming for certain businesses in the Financial Services sector as well.)
(Sanctions Regime compliance - see separate services for this on our website.)
Feel free to contact us, ideally by using the 'How can we help you?' form below.
The SRA is making changes which will take effect for the first time in the January 2027 sitting of the SQE1 (including for people doing a resit).
What are the changes?
More time to answer. The number of questions in each of the FLK1 & the FLK2 will be reduced from 180 to 170 (as the FLK1 & the FLK2 is each divided into a morning & an afternoon session that will be a reduction of the questions in each session from 90 to 85 questions). Crucially, the duration of each session is NOT being reduced. So, you will have more time.
Grouping of the questions. The SRA have written: "Questions in all subject areas will no longer be presented in both sessions of an FLK assessment. The questions in each FLK session will contain questions from the subject areas as shown in the table below. Ethics and Professional Conduct will however continue to be tested across all subject areas and can therefore be tested in each session."

Link to what the SRA say about this: https://sqe.sra.org.uk/news-item/2026/09/10/important-changes-to-sqe1-for-january-2027-onwards
Link to the SQE1 Assessment Blueprint: https://sqe.sra.org.uk/assessments/sqe1-assessments/sqe1-specification/sqe1-annex4
External QWE Confirmation Service
If you know of someone who needs an SRA regulated solicitor to confirm their QWE but have no-one in their organisation to do so - we can help. This service would apply to someone who is NOT qualified as a lawyer. Please see the link below and feel free to signpost them to us: QWE - External Confirming Solicitor Service - for Aspiring Solicitors
SQE2 Exemption Applications - Qualified Lawyers
Help for qualified lawyers with making their application for exemption from the SQE2 exam: https://hunningsconsultancy.co.uk/sqe2-exemption-for-foreign-lawyers-review-advice/
YouTube Videos on SQE, SQE2 Exemptions & QWE
https://www.youtube.com/@hunningsconsultancy999/videos
We’ve produced another CPD course. This one specifically updating you on the Data Use & Access Act 2025 (DUAA) now that all aspects have been brought into force. £30+VAT per view. Click▶Pay▶Watch▶Quiz▶Certificate Link: https://ingemar-s-site.thinkific.com/courses/data-act-2025-compliance-course
You’ll also find here CPD courses on AML & other aspects of Data Protection compliance: https://hunningsconsultancy.co.uk/hcl-launches-cpd-training-courses-data-protection-compliance/
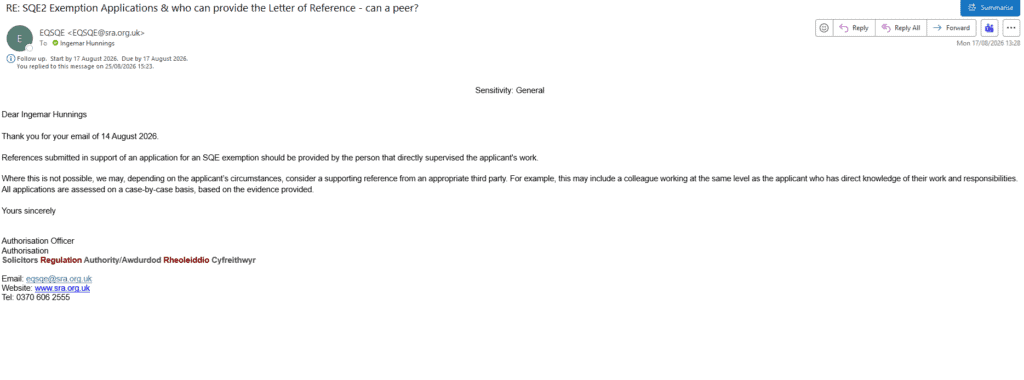
There appears to be a little more flexibility in the SRA's approach. Hitherto we had understood that the supervisor had to be someone who directly supervised the applicant's work. Indeed we had been told that if the applicant had no such person the application for exemption would not be granted and they would have to sit & pass the SQE2 exam.
However, we recently have received a reply from the SRA which indicates that they MAY apply a slightly more lenient approach. They might 'consider a supporting reference from an appropriate third party'
Below is an image of their reply.
Link to a video about this on our YouTube channel: https://youtu.be/6Nu0AsPVCXs
SQE2 Exemption Applications - Qualified Lawyers
https://hunningsconsultancy.co.uk/sqe2-exemption-for-foreign-lawyers-review-advice/
External QWE Confirmation Service
If you know of someone who needs an SRA regulated solicitor to confirm their QWE but have no-one in their organisation to do so - we can help. This service would apply to someone who is NOT qualified as a lawyer. Please see the link below and feel free to signpost them to us: QWE - External Confirming Solicitor Service - for Aspiring Solicitors
YouTube Videos on SQE, SQE2 Exemptions & QWE
https://www.youtube.com/@hunningsconsultancy999/videos
We have received the following email from Companies house regarding changes that will come in to effect from April 2028. In summary ALL companies, including Small & Micro Companies, will then be required to file Profit & Loss accounts and to file using commercial software. However, small and micro-entities will be able to opt out of having their profit and loss accounts published on the public register. (Details of how to opt out to be confirmed in due course.)
Link to more info on the governemnt website: Companies House to bring in changes to accounts filing from April 2028 - GOV.UK
What do we think? Actually the reporting and checks on Companies House are very lax. They need to take steps to tighten things up and work to spot and close down fraud. We don't have a problem with filing the Profit & Loss accounts. They are generated anyway by our accountants. However, we will be using the opt out for public publication of them. Not that we have anything to hide - but just that that is out private information and so we will keep them private until we grow to such a size that we cannot do so.
Link to a video we've put on YouTube where Ingemar, our lead consultant, discusses this: https://youtu.be/aik39yVCZjU
Wording of the email:
"This is an official email from Companies House, sent to all registered email addresses. The information in this email is relevant to all companies registered in the UK. If you’re a third-party agent who has received this email on behalf of a company, please forward this message to the company directors of all companies you work with.
This email provides an update on changes to how companies will file their annual accounts from 1 April 2028. Companies will have received an email about these changes last year. Please read this update carefully as some details have changed.
The government has now confirmed how the Companies House accounts reforms measures set out in the Economic Crime and Corporate Transparency (ECCT) Act 2023 will be implemented. Under the ECCT Act, the government will reform how companies report information and what information they report when filing their annual accounts with Companies House.
This update follows a pause in implementation last year and extensive engagement with stakeholders to consider their views around the impact some of the reforms may have on companies.
The government has taken the decision to proceed with the reforms. These include:
| requiring small companies and micro-entities to file profit and loss accounts, as other companies do |
| all companies having to file their accounts at Companies House via commercial software |
| other smaller technical amendments. |
However, to help address concerns, the government is introducing two changes:
| Opt out of profit and loss publication: small and micro-entities will be able to opt out of having their profit and loss accounts published on the public register. Details of how smaller companies can opt out of publication will be confirmed in due course.Postponed timings: these reforms will now come into effect on 1 April 2028, rather than 1 April 2027. This will give companies additional time to prepare, with one full accounting year plus nine months (a total of 21 months) to get ready. |
In line with the changes, our web and paper routes will be closed for accounts filings from 1 April 2028, but will remain open for other statutory filings."
The SRA has published the result of its review into these 2 topics and has published its proposed changes to the rules. They intend for them to come into force in early 2027 with a phased introduction. That is soon, given the changes firms will have to make - so firms show consider this now and plan action. Links to the full report from the SRA of its conclusions and to the draft rule changes are below.
Accounts Rules Changes - Accountant’s Reports
The SRA has written:
"The alterations to our regulatory arrangements for the accountants’ reports regime comprise:
• a requirement for all non-exempt firms to submit their accountants’ reports to us,
whether qualified or unqualified
• an annual declaration requirement for all client money-holding firms confirming their
status and key information relevant to the accountants’ reports regime
• the extension of fixed financial penalties to cover defined procedural breaches of the
accountants’ reports requirements, such as late or non-submission."
To check the rules for exemption from the requirement to have an annual Client Account Audit see this link: https://hunningsconsultancy.co.uk/solicitors-when-do-you-need-a-client-account-audit/
The SRA has, for the time being, not made it a requirement for the accountants to send a copy of the report direct to the SRA. But they might in the future. For the time being the responsibility for making sure the SRA receives your Accountant's report rests with the law firm.
Link to access the draft rules changes: https://hunningsconsultancy.co.uk/wp-content/uploads/2026/06/draft-sra-accounts-rules-and-rdpr-post-consultation.pdf
Compliance Officers Changes
The SRA has made these changes by altering the Firm Authorisation Rules.
The SRA has written:
"The proposed alterations to our regulatory arrangements on compliance roles comprise:
• new authorisation eligibility criteria, to prevent owners or managers who can
unilaterally determine or direct significant management decisions from holding one or
both key compliance roles in firms with:
- an annual turnover over £600,000 in the previous accounting period and/or
- a client money balance over £2,000,000 at any point in the most recent
accounting period.
• a partial exemption for sole owner-managers firms which are in scope by virtue of
meeting the client money threshold, preventing individuals from holding the COFA
role, only
• an exemption for firms which exceed the client money threshold because of
anomalous transactions which are not representative of the firms’ usual or expected
business activities."
Link to access the draft rules changes: https://hunningsconsultancy.co.uk/wp-content/uploads/2026/06/draft-sra-authorisation-rules-post-consultation-Compliance-Officers.pdf
This will involve some reorganisation for larger firms. Smaller firms within scope may face some challenges as they may not have enough staff to share around the roles!
The Full SRA Response to the Consultation
Please see here where you may access the full SRA response: https://hunningsconsultancy.co.uk/wp-content/uploads/2026/06/Full-Consultation-Response-Accounts-Rules-Compliance-Officers.pdf
Contact Us for Compliance Assistance
For example: if you need 121 COFA training.
Please fill in the form if you require help with anything to do with the SRA Rules and the SRA Accounts Rules. Please fill in the form below.
In UK vs Secretary of State for the Home Department ([2026] UKUT 00081 (IAC)), the UK Upper Tribunal Immigration and Asylum Chamber has held that whenever a legal practitioner uploads confidential client documents into open-source, non-specialist AI such as ChatGPT, the legal practitioner waives the privilege enjoyed by the client and breaches the confidentiality obligations owed to them. Once uploaded into open-source AI, such documents may enter the public domain, irrespective of their importance.
Here is a link to the case report: https://www.iclr.co.uk/document/2026001222/2026ukut81iac_TNA/html
No surprise here for us. Be careful!
Do you have an AI Usage Policy? Do your staff need training on AI? If so we can help (fill in the form below).
For on-line Data Protection Training courses: https://hunningsconsultancy.co.uk/hcl-launches-cpd-training-courses-data-protection-compliance/
The Law Society has issued guidance with a Q&A of 20 questions.
Here’s the link: https://www.lawsociety.org.uk/topics/property/q-and-a/hmrc-mandatory-tax-adviser-registration
Create with them an agent services account by 18th May, or if you have one, on 18th May make sure that your account meets the new registration conditions. Firms will have 3 months from 18th May to complete their registrations. Registration is free. HMRC are creating a video. If you don’t register, you may no longer be able to communicate with HMRC.
The Home Office has updated its guidance to version 3.0 – which supersedes all earlier versions. This is of relevance to anyone who does immigration work. Here is the link to the guidance: https://www.gov.uk/government/publications/working-with-immigration-advisers-caseworker-guidance/working-with-immigration-advisers-caseworker-guidance-accessible

